Key Takeaways
- Cost-plus pricing can provide a simple, transparent pricing baseline, but cost should not be the sole basis for setting prices.
- The biggest risk is ignoring customer value, willingness to pay, demand and competitive conditions.
- Fixed markups can limit value capture and may prevent businesses from benefiting fully from cost efficiencies or product differentiation.
- Strong pricing teams combine cost data with customer and market insights to improve price realisation and margins.
- Moving beyond cost-plus pricing requires cross-functional buy-in, clear pricing ownership, effective processes and the right capabilities.
Cost-plus pricing is a cost-based pricing method in which a business calculates the cost of producing or acquiring a product or service and adds a predetermined markup to establish its selling price. The resulting price is intended to cover the underlying cost and provide a return to the business.
Many pricing professionals view cost-plus pricing as a limited, backward-looking approach because it starts with costs rather than customer value. However, it can provide a useful starting point when costs are predictable, cost recovery is important or contracts require transparent pricing calculations. Its main limitation is that the resulting price may not reflect customer willingness to pay, demand or competitive conditions.
In this article, we explain how cost-plus pricing works, including the cost-plus pricing formula, markup and margin calculations, and practical examples. We also examine the advantages and limitations of cost-plus pricing and explain when businesses should consider customer value, willingness to pay, demand and competitive conditions alongside cost.
>Download Now: Free PDF How to Drive Pricing Strategy to Maximise EBIT Growth
Table of Contents
- Main Guide:
- Related Pricing Guides
See whether your pricing is under control
Cost-Plus Pricing: How It Works, Formulas and Limitations
What Is Cost-Plus Pricing?
Cost-plus pricing is a pricing method in which a business calculates the cost of producing a product or service and adds a markup to determine the selling price. Alternatively, a business can calculate the selling price from a target gross margin using a separate formula. In simple terms, the price is based on what the item costs the business rather than primarily on customer value or competitor prices.
The approach generally works in three steps:
- Calculate the cost: Determine which costs should be included in the price calculation, such as production, overhead or other relevant costs.
- Apply a markup or margin: Add a fixed amount or percentage of the cost. For example, a 200% markup on an $8 product adds $16, resulting in a selling price of $24. Alternatively, a business can calculate its selling price by working backwards from a target gross margin, using a different formula.
- Set the selling price: The resulting figure becomes the initial selling price. In the biscuit example later in this article, an $8 cost plus a 200% markup produces a $24 price.
Businesses commonly use cost plus pricing when they need to establish an initial price for a new product or review an existing price. However, the method creates important questions about which costs to include, what markup to apply and whether the resulting price reflects customer value and competitive conditions.
These questions explain why businesses continue to consider cost-plus pricing, despite the limitations it can create when used as the primary basis for setting prices.
Cost-Based Pricing vs Cost-Plus Pricing
Cost-based pricing is a broad approach that uses the cost of producing or acquiring a product or service as the starting point for setting prices. Cost-plus pricing is one specific form of cost-based pricing, in which a predetermined markup is added to the underlying cost. Businesses may favour this approach because it provides a clear basis for cost recovery and makes pricing calculations easier to explain. However, accurate cost data does not establish what customers are willing to pay, so businesses should also assess market conditions before finalising their prices.
Issues of Cost Plus Pricing in the Forex Market 📉 Podcast Ep. 73!There are many situations where a business may consider using a cost-plus approach to set or review prices. This can be particularly useful when costs are measurable, margins need to be protected, or a business needs a straightforward starting point for a new product or service. However, cost should generally be considered alongside customer value, demand and competitive conditions rather than treated as the sole determinant of price.
Cost-based pricing
Cost-based pricing starts with the cost of producing or acquiring a product or service and uses that cost as the basis for setting a price. Cost-plus pricing is one form of cost-based pricing, where a markup or margin is added to the underlying cost.
Cost-plus pricing formula
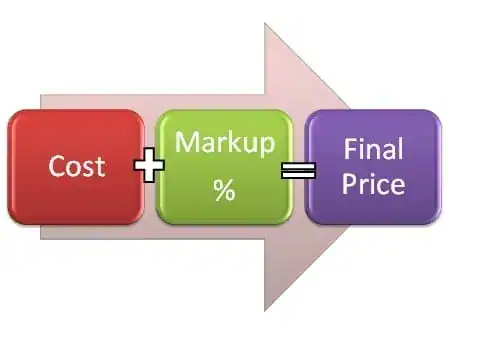
The basic cost-plus pricing formula adds a predetermined markup amount to the cost of a product or service to calculate its selling price. If C represents the cost, A represents the amount added and P represents the selling price, the formula is:
P = C + A
Companies that use cost-based pricing
Businesses may use cost-plus pricing when costs are measurable and contracts or projects require a clear basis for calculating and recovering costs. Examples can include certain construction and engineering projects, government contracts and specialised manufacturing arrangements. However, the suitability of this approach depends on the contract structure, how costs are allocated and the commercial requirements. Businesses may also consider market conditions, competitive pressures and customer value when determining the final price.
Cost-Plus Pricing Example in Construction
For example, a building materials business might use cost-plus pricing to estimate the price of a job (say $56,451). The company’s key stakeholders discuss the appropriate markup. They consider annual job volumes, overhead costs and target profits before deciding how much to add.
Based on these factors, the company adds $32,987 to the job’s costs; then the company would set the price of doing that job at $89,438.
Markup pricing
Markup pricing is another cost-based method. It adds a standard percentage of the item’s cost to determine the selling price. A company may use the same markup percentage across all its products or apply different standard percentages to different product categories.
Markup is calculated by dividing the amount added to the original cost by that cost, then multiplying by 100 to express the result as a percentage.
M = (added amount/C) x 100
Cost-Plus Pricing Formula: A Retail Example
To calculate a selling price using a percentage markup, first convert the markup percentage into a decimal by dividing it by 100. Multiply this figure by the product cost to determine the markup amount, then add that amount to the original cost. The formula is:
P = C + [(M/100) × C]
For example, to set your initial prices on a line of luxury biscuit boxes for Christmas, a retailer might apply a 200% markup. If the retailer pays $8 for a particular brand of luxury biscuit box selection, it would use the following calculations to set a price of $24 for this line of luxury biscuit boxes:
P = $8 + [(200/100) × $8]
P = $8 + (2.0 × $8)
P = $8 + $16
P = $24
Cost-plus pricing method
You may now be wondering how companies determine the markups they use. Many procurement teams ask the same question. For many distributors and retailers, markup levels are governed by tradition (they have always done it this way) or simple rules of thumb (a lot of rough estimates and guessing). For example, a wholesaler might apply a standard markup to merchandise costs, although the appropriate percentage varies significantly by industry, product category, customer segment and competitive conditions.
Keystone Pricing in Retail and Merchandising
Keystone pricing is a retail markup approach in which the selling price is set at approximately twice the item’s cost, representing a 100% markup.
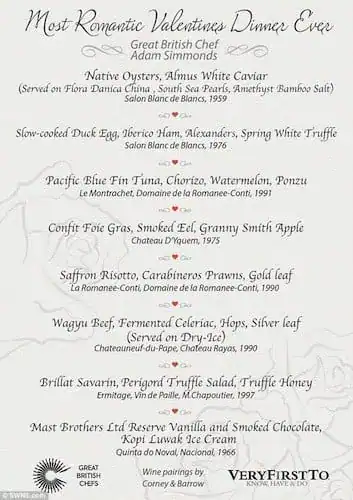
Restaurants have also historically used food-cost percentages and markup rules as starting points for menu pricing, although the appropriate approach varies by restaurant, menu category, location and operating model.
An interesting point to note is that when goods pass through multiple businesses before reaching the consumer, successive markups can be applied at each stage of the distribution channel.
The earlier $24 example assumes the retailer buys the biscuits directly for $8 and applies a 200% markup. When a distributor is introduced, the retailer’s acquisition cost increases to $9.60. If the retailer then applies a 100% markup to its acquisition cost, the final selling price becomes $19.20. This is a separate simplified scenario from the earlier direct-to-retailer example, which used a 200% markup.
Using the luxury biscuit example, a simplified pricing structure might look like this:
Manufacturer: $8.00
Distributor: $8.00 cost + 20% markup ($1.60) = $9.60 wholesale price
Retailer: $9.60 cost + 100% markup ($9.60) = $19.20 retail price
Consumer: $19.20
This illustrates how successive markups can significantly increase the final price paid by the consumer. In this example, the retailer adds $9.60 to its acquisition cost, representing a 100% markup on the distributor’s $9.60 wholesale price.
Cost-plus margin pricing
Another way to calculate a selling price using cost information is to work backwards from a target gross margin. This approach uses a gross-margin pricing formula rather than simply applying a markup percentage to cost. Many businesses use cost-plus margin pricing because they want the process of calculating a price to be heavily influenced by the profit goals of the organisation. Many managers aim to maintain a specific margin percentage to meet their targets. Consequently, they set their product margins at a certain level aligned with their profit goals and work from there.
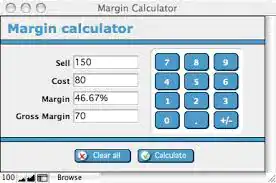
Markup and gross margin are two different ways of measuring the amount a business earns above its product cost. Markup expresses the amount added to cost as a percentage of that cost, while gross margin expresses the difference between the selling price and cost as a percentage of the selling price. Businesses can use a target gross margin to calculate the selling price they need to achieve. The gross-margin formula is:
%GM = (added amount/price) x 100
Calculating a Selling Price from a Target Gross Margin
Businesses can convert the gross-margin percentage into a markup percentage or calculate the selling price directly using the following formula:
P = C/[1 – (%GM/100)]
A higher gross-margin target produces a higher selling price relative to cost, while a lower target brings the price closer to cost. Appropriate targets depend on the business’s economics, product category, operating model and competitive position.
How gross margin affects cost-plus pricing
Using gross margins in price setting helps businesses incorporate profit goals into pricing decisions. However, customers may challenge price increases if they do not see sufficient value to justify the higher price. Businesses should therefore support pricing decisions with clear commercial reasoning rather than relying solely on a target margin or a rule of thumb.
Advantages of cost-plus pricing
Cost-plus pricing can offer several practical advantages, particularly when businesses need a simple and consistent way to establish prices.
- Simple to calculate: Businesses can start with a known cost base and apply a predetermined markup or margin.
- Transparent: The underlying cost and markup can provide a straightforward rationale for the price.
- Useful for cost recovery: Cost-plus pricing can help businesses ensure that relevant costs are considered when setting prices.
- Consistent: Standard markups can create greater consistency across products, projects or customer transactions.
- Useful as a starting point: Cost information can provide an initial pricing reference before the business considers customer value, willingness to pay, demand and competitive conditions.
However, these advantages do not mean that cost should determine the final price in every situation.
Five Limitations of Cost-Plus Pricing
Cost-plus pricing can provide a simple and transparent starting point for setting prices. However, relying on it as the primary pricing method can create several problems, particularly when customer value, demand and competitive conditions differ significantly from the underlying cost base.
1. How do you calculate costs for cost-plus pricing?
In a traditional cost-plus pricing approach, businesses calculate the cost of producing or acquiring a product and add a predetermined markup. However, the first challenge is deciding which costs should be included in the calculation.
This may seem a simple question. However, we have to decide what costs we should include. Is it total average costing, marginal costing, etc?
Think of a cost-based pricing example where a company sells 100 teddy bears.
If someone doubles the order to 200 bears, what would the cost of the bear be for the calculation?
Should they set the price for the new bears at the average cost (i.e. dividing the factory, rentals, machinery costs, etc across the new bears)?
Also, should they reduce the cost for the original 100 bears as the same factory is producing more bears?
Or should it just be the marginal cost of the bears?
In an extreme example, if the marginal cost of bear production is zero, should they give that bear away for free?
We might have heard somebody say, “I have worked in companies where average costing was not giving us a ‘low enough’ price.”
What ended up happening was that they started to remove costs that were deemed “not appropriate.”
2. What markup should you use?
Even when a business can calculate its costs accurately, deciding what markup to apply can be difficult. Should the business add 10%, 20% or even 600%? There is no universal markup that works across all products, industries and customer segments. The appropriate percentage depends on customer value, competitive conditions, demand, cost structure and commercial objectives.
3. Can fixed markups limit the financial benefits of efficiency improvements?
This is a slightly funny way of looking at things but highlights the inherent flaws in this approach.
If a business applies a fixed markup percentage to unit cost, an 80% reduction in unit cost will also reduce the dollar amount added through the markup if the selling price is recalculated using the lower cost. Although the markup percentage remains unchanged, the business may capture less dollar value from each unit. This illustrates why relying on a fixed markup alone may prevent a business from fully considering the additional value created through efficiency improvements.
4. Does cost-plus pricing reflect customer value?
What if you have a highly differentiated product or service? Customer willingness to pay may be significantly higher than the cost-plus price suggests. A beer may cost relatively little to produce, for example, but customers may be willing to pay very different prices depending on the location, experience and perceived value. Similarly, business-class customers are paying for substantially more value than the underlying cost difference alone would suggest.
5. Can cost transparency weaken your negotiating position?
What if your B2B clients know that you apply a 50% markup to a product? They may use this information to challenge your pricing or negotiate a price reduction. However, customers should not confuse markup with gross margin. A 50% markup does not mean the business earns a 50% gross margin. For example, a product costing $100 with a 50% markup sells for $150, producing a gross margin of 33.3%.
Some customers argue that suppliers should earn no more than their own 20% margin. They may use this comparison to demand price reductions. Therefore, avoid giving customers unnecessary reasons to challenge your margins.
When Does Cost-Plus Pricing Become a Problem?
Cost-plus pricing provides a straightforward way to establish a price from the underlying cost base. However, when it becomes the primary pricing strategy, businesses risk overlooking competitor prices, customer willingness to pay, demand and the value created by the product or service. The question is therefore not whether cost-plus pricing is good or bad, but whether it is being used appropriately for the commercial situation.
See how pricing breaks in practiceHow to Move Beyond Cost-Plus Pricing
One major limitation of relying too heavily on full-cost pricing is that it can leave value on the table. An input-based approach may produce a price that covers costs and delivers a target margin, but it does not necessarily reflect the value created for customers. Businesses should therefore consider customer value, competitive positioning and demand when reviewing existing prices rather than treating cost as the final answer.
Consider what value your product actually offers and where it is differentiated. Then calibrate your pricing against market positioning, competitor prices and customer willingness to pay. Monitoring price-value differentials by product and segment can help identify where prices are too high, too low or appropriately positioned.
Whether you work in government contracting or B2B sales, understanding the value your customers place on your product or service is key.
〉〉〉 Get Your FREE Pricing Audit 〉〉〉
Cost-plus pricing vs value-based pricing
If you are the sole provider of a highly differentiated product, the cost to produce the service may have less influence on the price than customer willingness to pay and the value created.
Value-based pricing is not simply about charging a higher price. It involves setting prices according to the value customers perceive and receive, and their willingness to pay. Businesses still need to consider costs and competitive conditions, but these factors inform the pricing decision rather than determine the price on their own.
If pricing discussions focus primarily on full costs, direct labour and overhead allocation, businesses should also ask whether customer value, willingness to pay and competitive conditions are being considered. A pricing process that focuses only on cost may overlook opportunities to improve price realisation and profitability.
If you would like to learn more about how to build a world-class pricing team for your business, download our complimentary e-book, Five Ways to double EBIT or free pricing recruitment guides.
Don’t waste another dollar on the wrong pricing team strategy.
See whether your pricing is under control
Pricing Methods: 5 Things People Say When They Do Not Get Pricing
Pricing is often misunderstood, even within businesses that rely on it to protect revenue and profitability. Common misconceptions about pricing methods can make it difficult for pricing professionals to gain support for pricing improvements. Addressing these concerns requires clear explanations, commercial evidence and an understanding of how different stakeholders view pricing.
These misconceptions affect how businesses approach cost-plus pricing, value-based pricing and other pricing methods. The following examples highlight common objections pricing teams encounter when introducing pricing improvements and explain why these concerns need to be addressed.
Below are some of the common statements people say when it comes to pricing. We suggest you keep a bingo card and tick it off if you have heard of them. If you did, then you can give yourself a pat on the back. The next step and more challenging one is to try to win over the person to the side of pricing and revenue management.
How many of these statements have you heard before?
1. “You cannot just increase prices.”
This is one of the most common statements pricing professionals hear. It reflects a fundamental misunderstanding of the pricing profession and pricing methods, which is why we have listed it first. If you cannot address this concern, you may struggle to gain buy-in for pricing optimisation. A good answer to this question will enable you to move on to more complex questions such as below. See our blog on premium pricing strategy.
2. “Is this some sort of pseudoscience with magic numbers?“
This one can come up or a variation on it when the concepts of psychological pricing, relative pricing, anchoring or numbers such as $5.99 are brought up. This should be viewed as a good thing as it opens the door for more discussion.
3. “Our sales force will never accept this price testing method.”
This is a great indication as to how the business is actually set up and who carries power. It can also give you great insight into why margin erosion may be appearing. At this point, it may be a smart idea to think about how sales teams are incentivised.
4. “You need to know our costs or drive our costs down more.“
This concern often arises when an organisation is not sales-driven and instead relies heavily on a strict cost-based pricing strategy. Do the finance team have a large say in pricing strategy? This gives a great indication as to where your work should begin.
5. “It will not work for us, as our industry is different.“
We left this one to last, as it is probably one of the most common comments. Although the opportunities vary by industry, most businesses can identify ways to improve pricing processes, price realisation or profitability.
We do not intend to belittle the common queries made by non-pricing professionals. Of course, they can be valid concerns when not answered with a clear and comprehensive solution.
Different stakeholders often define price differently. The sales team may focus on the invoice price, while the CFO looks at the revenue the business ultimately retains. Customers assess whether the price reflects the value they receive, while distributors consider whether the price leaves sufficient room for a sustainable margin. These different perspectives highlight why businesses need a consistent approach to price management.
So what defines and indicates price?
Can you improve net price realisation and increase the amount your business ultimately receives? Net price realisation is the actual revenue retained from a sale after accounting for discounts, rebates, returns, warranties, commissions, allowances and other relevant deductions. It provides a more complete picture of the price achieved than the original list price or invoice price alone.
There are several elements to price management. The first is achieving the optimal price for each good or service. The second is managing your product mix and services to achieve the optimal price for a set of customer transactions.
The gap between list price, invoice price and final realised revenue can be substantial. Co-op funding, early-payment discounts, volume rebates, freight allowances, returns and other deductions can all reduce the amount a business ultimately receives.
For example, if a business has a 10% operating margin and can increase realised prices by 1% without materially affecting volume or costs, much of that incremental revenue can flow through to operating profit. The precise impact depends on the business’s existing margin structure and cost base.
Do you spend as much time thinking about price as you do thinking about costs? We will discuss 6 things that you need to be attentive to that can help improve your pricing and profits.
Here are 6 steps to consider that can improve your pricing methods and profits:
Appoint a clear executive-level owner of pricing
Most organisations do a great job of managing pricing execution and deals flow. Your pricing manager may be doing a good job tactically, however, they should also be thinking strategically. It is great to have a capable and experienced owner of pricing strategy who can think ahead into what to do more in the future.
Systematic pricing reviews remain an important part of effective pricing management, particularly when businesses need to respond to changing costs, customer demand and competitive conditions.
What to do: Delegate one of your executive team, most likely the VP of Marketing or CMO, with building a pricing team and enabling them to develop a pricing improvement plan and process.
Optimise your product range
Classify your customers and understand which ones are price sensitive. Have a basic price fighter in your range that will meet their needs without disrupting your full product line pricing.
What to do: Look at your product pricing methods vs. your user segmentation again.
Align sales compensation with revenue and margin growth
If your reps are paid with basic wages (not for profits or price improvement), what incentive do they have to fight for the best price?
If you were selling and could make 5% commission on $1000 with little effort, or 5% commission on a $1010 sale with some effort and risk, what would you do? The 1% price lift is worth a negligible amount to them but a huge amount to your bottom line!
What to do: Consider having, at a minimum, your sales leaders receiving an incentive on the expansion of either average selling price or gross margin.
Review your price waterfall annually
Check on all price deductions made prior to the final net price.
Are programs such as co-op still pulling their weight as you’ve shifted your pricing strategy to inbound marketing, pulling away from distributors to create demand? Do customers take an early pay discount when paying after the early pay period has expired?
Once you have established your price waterfall, compare it to your leading competitors. When you do, you are pushed to match invoice price plus you have more attractive trade terms. Often, your customers and sales team are not discussing these factors during price negotiations.
What to do: Review your pricing methods, selling terms and price structure annually, and compare them with those of your competitors.
Understand your customers’ value
Do those who set your prices truly understand your customers’ value? Do you have a pricing playbook and value-based pricing method that continuously reinforce the value of your products? What diagnostic tool did your team use to improve pricing?
What to do: Ask your customers why they buy from you. This is a value discovery program.
Set expectations for annual price improvement
Most businesses are worried about losing market share. Therefore, creating a culture of price improvement will ensure pricing is always top-of-mind for your commercial function.
What to do: Establish an annual price improvement goal and review progress at regular intervals.
〉〉〉 Get Your FREE Pricing Audit 〉〉〉
Price optimisation is not simply about increasing prices or sacrificing sales volume. It involves identifying pricing leakages, improving net price realisation and balancing customer value, demand and profitability. Regular reviews can help businesses identify where pricing practices are creating unnecessary margin pressure or missing opportunities to capture value.
In a very competitive business environment, companies need to capture the full value of their products. They can do it using different distribution channels in order to be successful. Focusing on these steps can help businesses identify pricing improvement opportunities and begin implementing changes. The timing and commercial impact will depend on the organisation’s pricing capabilities, processes and market conditions.
See our blog on how pricing can help when making a business plan. Also, see our blog on 5 real issues with a cost plus pricing strategy and types of price elasticity of demand.
See whether your pricing is under control
Cost-Based Pricing: Communication Skills for Pricing Leaders
Why is communication a prerequisite for pricing leaders?
At Taylor Wells, we often help businesses establish pricing teams and functions where pricing has not previously been recognised as a core part of the commercial proposition. In these organisations, cost-based pricing and cost-plus pricing can be strongly defended, even when they do not adequately reflect customer value or market conditions.
Cost-plus pricing is often criticised because it can create unintended commercial incentives. For example, when a selling price is recalculated using a fixed percentage markup, reducing the underlying cost also reduces the dollar markup added to the price. Conversely, a higher cost base can produce a higher selling price without necessarily reflecting greater customer value. Businesses therefore need to consider whether their pricing approach rewards efficiency and captures the value created.
Another limitation is that a cost-based pricing formula does not, by itself, account for customer willingness to pay or competitor prices. Ignoring these factors can result in prices that are poorly aligned with market conditions.
This article explores the challenges pricing leaders face when introducing new pricing approaches, particularly how they can gain stakeholder support for pricing optimisation and value-based pricing. A pricing leader needs to operate as a business leader rather than within an isolated function such as finance, risk or legal. Successful pricing transformation requires support from sales, marketing, finance, operations and the executive team. Without this cross-functional buy-in, even well-designed pricing initiatives can be difficult to implement.
How to broach the elephant in the room? Cost-based pricing may not be the best approach in every situation.
I was chatting to a friend the other day from a company where I used to work at. I was asking about the commercial strategy and who is setting a pricing strategy. He said, “How can they set prices when they do not even know the costs?” At that point, I do not have enough time to go down the road of explaining value-based pricing. Also, I do not want to criticise my friend who seems so committed to cost-based pricing strategy. Opinionated people exist. They stick to what they believe in. They see it as a form of hearsay or lazy/shady marketing waffle when they hear anything different.
It can be an exhausting experience winning buy-in from multiple functions for a move to value-based pricing. However, it is vital to build any pricing transformation. In fact, we view it as laying a solid foundation for the transformation. Otherwise, you are sure to find the optimisation program will flounder as if on quicksand.
There are sometimes strategic and tactical reasons to use cost-plus pricing. When used in the right circumstances, cost-plus pricing can provide a simple and transparent pricing baseline, particularly where costs are predictable and contractual or regulatory requirements make cost recovery important. However, it should generally be tested against customer value, demand and competitive conditions rather than used as the sole basis for pricing.
Cost-plus pricing is often easier to communicate because businesses can explain the underlying cost and markup. However, transparency does not automatically make a price commercially appropriate, fair or aligned with customer value. Cost-plus pricing can offer transparency when businesses can clearly explain their costs and markup. However, it does not automatically guarantee fair or nondiscriminatory prices, even when costs are accurately measured. Many businesses also struggle to calculate their costs precisely, and their estimates may rely on guesswork.
Cost-plus pricing and value-based pricing start from different points. Cost-plus pricing begins with the cost base, while value-based pricing begins with customer value and willingness to pay. In practice, businesses can use cost information alongside value and market information when making pricing decisions.
Communicating Cost-Based Pricing Decisions Effectively
At Taylor Wells, we believe effective pricing education and recruitment can help businesses develop the capabilities needed to improve commercial performance. While the benefits of value-based pricing may be clear to experienced pricing professionals, introducing a different approach requires clear communication and evidence that other stakeholders can understand and apply.
Usually, this is the moment when value-based pricing becomes clear to us. The challenge in spreading the word to others is helping them to have their own light-bulb moment. More often, the trick can make them believe that they thought of it themselves!
Implications for Moving Beyond Cost-Plus Pricing
Cost-plus pricing can be useful in situations where businesses need a transparent and consistent way to recover costs, particularly when costs are predictable and contractual or commercial requirements make cost recovery important.
However, cost-based pricing can become problematic when businesses use it as the primary basis for setting prices. A cost-based price may not reflect what customers are willing to pay, how much value the product or service creates, or how the business is positioned against competitors.
Businesses with a genuine cost advantage may also have an opportunity to capture more value than a standard markup allows. Rather than automatically passing cost savings through to customers, they should consider whether those savings create additional economic value that can be retained through better pricing.
〉〉〉 Get Your FREE Pricing Audit 〉〉〉
Conclusion
Cost-plus pricing is not inherently a bad pricing method. In the right circumstances, it can provide a simple and transparent baseline for recovering costs and establishing an initial price.
The problem is relying on cost as the primary determinant of price. Costs tell you what it takes to produce or deliver something, but they do not necessarily tell you what customers are willing to pay or how much value your product or service creates.
For businesses looking to improve profitability, cost-plus pricing should therefore be treated as one input into the pricing decision rather than the entire pricing strategy. Combining cost information with customer value, willingness to pay, demand and competitive positioning gives businesses a stronger basis for capturing the value they create.
See whether your pricing is under control
Pricing System to Build a Culture of Collaboration in 100 Days
Moving beyond cost-plus pricing requires more than introducing a new pricing formula. Businesses also need the organisational capabilities, processes and collaboration to make better pricing decisions. Finance, sales, marketing, operations and pricing teams must work together to understand costs, customer value and commercial objectives.
As businesses respond to changing market conditions, executive teams need pricing systems that support better commercial decisions, clearer accountability and more effective collaboration across departments.
Executive teams are therefore encouraging employees to collaborate, develop new pricing and management skills,, and adopt more effective pricing processes to improve commercial performance.
Yet, dealing with a consistent stream of resistance and complacency from their people and customers has been a tough problem many businesses have not overcome.
For some executives, it was a no brainer, they were captivated by the pricing potential in the business and wanted to be the one who generated significant wealth for the business and its customers.
Many businesses were transitioning to the next phase in operations, and this in turn required a complete rethink of their current pricing system and sales operations.
The problem was, though, they also saw a proliferation of people problems attached to moving the business from cost-plus pricing system to more sophisticated pricing strategies and analytics.
Many gave up.
At first, CEOs and executive teams asked their managers and teams to work together to make the pricing project a success.
But often the message to ‘play nicely’ and accept new pricing practices were not getting through to the bottom line.
Teams across supply, pricing, sales and finance functions would resist or at best comply with broader directives to embrace more sophisticated pricing and sales strategies and analytics.
So, businesses started to recruit some serious leadership muscle and brainpower.
What a smart pricing system can do
Instead of demanding changes to outdated thinking and pricing processes, smart leaders first explored why people resisted pricing changes.
Most businesses found that value-based pricing was being labelled ‘consultant jargon’ by key leaders and influencers in the business, i.e., difficult to execute, right in principle but not in practice, etc.
They heard people say that dynamic pricing only works for airlines and would never work in this business…
Companies observed their sales, supply, operations and finance teams’ insecurity surface as they began to change the most basic of operations and price administration.
So leaders started to launch campaigns to their peers, teams and stakeholders in an attempt to re-brand alternative pricing approaches as “pricing transformation.”
They also began to teach stakeholders and customers on how to think, feel and implement more sophisticated market strategies. They also re-framed their value relative to their customers’ key value drivers and better KPIs (not just volume targets).
Once the sales teams started to see the results of reconnecting with customers using pricing as a device for wealth creation across the value chain, more teams became interested in working together to achieve collective goals.
Very quickly, the mission for all teams was to find innovative ways to deliver more complex business outcomes.
Silos, turf wars and unhelpful patterns of thought diminished at the same rate as teams internalised better sales and pricing into their everyday thinking and routines.
Value-based pricing, algorithmic pricing and AI are important areas of pricing and revenue management. Their relevance and adoption vary across industries and businesses.
Reframing pricing projects can do more than change their image. Today, many leaders present pricing as a continuous learning process rather than a ‘set and forget’ exercise.
When you associate pricing with transformative learning, you introduce 3 crucial psychological and pricing devices:
- psychological (changes in understanding of the self)
- convictional (revision of belief systems)
- and behavioural (changes in price practice and habits)
Taylor Wells observes some of the best leadership executives using some form of psychological intervention to identify and address a range of people and business problems, from team performance, change management, recruitment, to strategic planning and implementation.
Team underperformance can create significant costs for businesses through lost productivity, poor decision-making and ineffective execution.
〉〉〉 Get Your FREE Pricing Audit 〉〉〉
Conclusion
Moving beyond cost-plus pricing requires more than a change in formulas. Businesses must also address resistance to new pricing practices, build cross-functional support and develop the capabilities needed to apply customer and market insights. These changes help pricing teams move towards more effective, value-based decisions.
See whether your pricing is under control
Distributor Pricing Model to Lock in Cash and Capture Value
What makes an effective distributor pricing model for B2B businesses selling products that are increasingly commoditised and competitively priced? The answer involves more than setting prices. Distributors need to understand customer value, manage pricing complexity and protect margins across products, customers and channels.
As markets change and whole industries are disrupted, the business models in the distribution sector are firmly in the process of continuous improvement. However, change is not consistent.
Two broad types of transformation are emerging across the Australian distribution sector. The first focuses on immediate cost reduction in response to commoditisation, margin pressure and declining cash flow. The second involves developing more differentiated, value-based business models and processes. These businesses are pursuing innovation and profitable growth by demonstrating their value and using pricing and revenue initiatives to improve performance.
The distribution industry then is changing overall for the better. And, now more than ever, distributors are seeking to reconnect the business to their customers. They are procuring higher-margin products and services that customers need and value, eliminating stock that drives up operating costs, and pricing products and services appropriately rather than underselling them. Unfortunately, many pricing transformations fail to deliver their expected results.
This article examines how B2B distributors can improve pricing across procurement, finance, operations, strategy, product design, product rationalisation and technology. It explores how a better understanding of internal costs, supply-chain economics, customer needs and market conditions can help distributors capture value and respond to competitive pressure.
At Taylor Wells, we strongly believe that better people, value capture mechanisms and price data analytics can help distributors build competitive advantage and improve profitable growth more effectively than traditional approaches.
By the end of this article, you will learn the 5 best ways to capture more value using the latest distributor pricing model.
Why Pricing Is a Key Profit Lever for Distributors
Pricing is the most powerful lever for increasing and improving gross margins and boosting profits for a distributor. Because price typically flows more directly through to revenue than volume or cost changes, even a small improvement in realised price can have a disproportionate impact on profitability when volume and costs remain broadly stable.
Price is top of mind for most customer procurement teams so you need to ensure that your prices are right. Procurement teams focus on cutting costs, and they see your line of business as a means to do it. You need to demonstrate the value of your product portfolio. So that they don’t cherry-pick at line items and request excessive price reductions.
Unfortunately, most distributors struggle with striking a fair and equitable value exchange. The price data structures are commonly full of holes and skills shortages and unreliable and price complexity slows down vital progress. This is particularly important when developing list-price strategies and implementing price optimisation.
For example, Taylor Wells has worked with a B2B distribution business with more than 20,000 SKUs, over 2,000 customers and five different market groups. Based on the number of SKUs, customers and market groups, the business could face a very large number of potential pricing combinations. The actual number of price records required would depend on how the business segments customers, structures its prices and manages commercial agreements.
In the future, then, to be a successful distribution business, consider price optimisation. Price optimisation helps distributors sort out price complexity, but more importantly speeds up profitable revenue growth. Improving pricing helps sales teams generate more profitable sales and enables executives to make better strategic decisions.
Overcoming Misconceptions: Key to Optimise Price
Skilled salespeople and even pricing teams still believe that increasing prices also means losing deals. Most especially if the competitors offer the same products. They may also argue for vigorous excessive discounting to make big customers happy and achieve their volume goals. However, the truth is more nuanced as revealed by qualitative and quantitative research.
So, how do pricing teams overcome these misconceptions and increase their win rates? Experienced pricing teams can improve win rates by estimating the total value customers receive and understanding how much they are willing to pay for both commodity products and value-added offers. Some of which are: one-stop shopping in all categories, a wide range of brands and models, convenient and fast delivery, flexible return policies, financial assistance for small and medium-sized businesses, and product expertise.
The urgency for change is stopping margin loss. Reducing prices continually is a race to zero profit. In the long term, businesses should base pricing decisions on each customer’s willingness to pay. They should also identify the non-price benefits customers value most. As teams improve their pricing capabilities, they can use these insights to refine their strategies.
Building a Distributor Pricing Model to Create Value
Some distributors have been pioneers in embracing pricing as a discipline. A growing number have invested in establishing pricing teams with a directive to provide profit margin improvement every year. They are also developing price architectures that reinforce pricing discipline and link to pricing analytics and other tools or software to capture value.
We have identified 5 key components of creating an income-generating distributor pricing model. A model that builds considerable, steady increases in margins, even during the economic crisis:
1. Create a dedicated pricing organisation.
We know a major foodservice distributor in Melbourne, for instance, where discretionary pricing by sales and excessive discounting was widespread. The business was facing jaws of death situation and they decided to establish a new pricing team to help them control pricing and protect margin. However, the business struggled to integrate the new pricing team. It took the business a couple of years to create a streamlined pricing organisation with support in branches locally.
The pricing team reported to the chief operating officer and had a directive to steer annual margin expansion. They decided to gain support in the business and build credibility by launching quick-impact measures in pilot locations. Their approach was to create enough eagerness to start a pull from several branch managers instead of a push from the ivory tower. They got some traction, but there were also key lessons learned and not everything they did worked.
The organisation subsequently invested further in its pricing capability and continued to pursue margin improvements through targeted initiatives, particularly in margin-constrained and high-growth segments. These initiatives formed part of the business’s broader effort to strengthen its commercial performance and customer relationships.
2. Use world-class processes in the pricing team.
Consider using best-in-class roadmaps, frameworks and input from pricing, sales and marketing teams to develop better price-setting and pricing-management processes. This includes steps, owners, inputs, and outputs. From here, your business is in the position to achieve the thoroughness, structure, or oversight required for consistent profit maximisation. Everyone is clear on what they need to do to achieve shared outcomes.
3. Adopt advanced analytics and digital transformation.
Distributors are increasingly using advanced analytics to identify pricing opportunities and support better commercial decisions. When supported by reliable data, effective processes and capable pricing teams, analytics can help identify margin improvement opportunities, reduce manual errors and improve pricing consistency. Pricing teams can also provide evidence-based guidance, benchmarks and data or quoting tools to support better decisions.
4. Tie sales with revenue and margin growth.
World-class sales organisations are tying compensation increasingly to both revenue and margin growth. Traditionally, sales representatives’ compensation has been aligned with volume rather than margins, sometimes leading to revenue growth at the expense of profit.
For example, an electronics distributor was experiencing margin erosion despite solid sales growth. The business discovered that sales representatives, whose incentives were based solely on sales growth, were offering free and expedited shipping and reducing prices to win deals. Following changes to its sales compensation model and pricing strategies, the business reported improvements in both sales and margin performance.
5. Build trust and buy-in.
Building trust with sales teams can be achieved by getting results quickly and working with the right people. For example, working with general managers to test pricing initiatives in specific branches can gain traction faster than approaching branch managers or sales teams directly. Once you have tested the initiatives and assessed their impact, share the results with the broader sales teams. Successful pilots can encourage these teams to request a wider rollout rather than requiring you to seek their approval at the outset. To build credibility within the broader sales-and-marketing function effectively, utilise general management in price trials and tests.
Discussion
Price improvement is not just a financial lever for immediate profitability. It is also a change management lever enabling B2B distribution to address the destructive issue of commoditisation.
Moving from a basic cost-plus distribution pricing model to value-based pricing is not easy. It requires a stronger value culture, effective price management and the right technology. For distributors managing thousands of SKUs, customer groups and market segments, historical cost-plus pricing and ongoing net price negotiations can create significant pricing complexity. Better pricing processes, data and technology are therefore important to managing this complexity.
Distributors increasingly need experienced talent across departments to support the transition to more sophisticated pricing models. Pricing executives, for example, can help redesign price architectures, move businesses beyond cost-plus thinking, develop value-based pricing approaches and structure performance rebates that encourage profitable growth. The right capabilities are important not only for developing better pricing strategies but also for implementing them effectively across the business.
Implications for Distributor Pricing
- Pricing improvements can create significant opportunities to strengthen distributor profitability. However, the commercial impact depends on the pricing initiatives implemented, customer responses, competitive conditions and the business’s ability to maintain sales volumes.
- Sales teams can sell more and better. They not only issue more accurate quotes to customers, they also improve customer experience. Customers hate waiting for prices when they are ready to buy.
- Distributors’ value to the customer increases as the firm focuses more on improving their performance in areas that matter to the customer: i.e., supply chain, customer service, technical expertise, innovative products.
- Rigorous pricing processes reduce missed opportunities, minimise the risk of excessive discounting and impose global consistency.
〉〉〉 Get Your FREE Pricing Audit 〉〉〉
Bottom Line
Distributors work in a fast-paced setting. Oftentimes, they are processing thousands of deals and transactions each day. Everything should be quick and easy. But often it’s not. Managing inventory, supply and cost fluctuations can be a nightmare. Let alone, restructuring your pricing and revenue management to realise additional price premiums.
With the support of an effective pricing team, distributors can move from a primarily transactional trading model towards a more customer-focused business. Over time, they can develop a price architecture that supports consistent price management, reflects customer value and helps protect profitability.
Sometimes, success can mean winning mega-deals in high growth segments, but oftentimes success in pricing is under the radar and focused on the long tail of products and customers.
A pricing team should help distributors implement an effective pricing model. This approach can improve revenue and margins, even in highly competitive or commoditised markets. It can also help leaders identify new growth opportunities.
Click here to download the whitepaper.
FAQ
〉〉〉 Contact Us for a FREE Consultation〉〉〉
For a comprehensive view on maximising growth in your company, download a complimentary whitepaper on How To Drive Pricing Strategy To Maximise EBIT Growth.
Are you a business in need of help to align your pricing strategy, people and operations to deliver an immediate impact on profit?
If so, please call (+61) 2 9000 1115.
You can also email us at team@taylorwells.com.au if you have any further questions.